SFR/BTR in 2027: Less Supply, More Opportunity?
Rent growth remains elusive and the recovery won't look the same everywhere. Read more in the first installment of our annual outlook series.
The SFR/BTR market is heading into 2027 with a more manageable development pipeline after two years of supply pressure, though the reset will be uneven.
Yardi Matrix’s September 2026 data capture that tension. Occupancy stood at 94.9 percent, 20 basis points below a year earlier, while advertised rents were up only 0.8 percent year-over-year and fell $4 in September, to $2,245.
Renters are still there, but operators have limited pricing power. As new supply recedes, the key question is where pressure will ease first, and whether occupancy, concessions and other operating metrics improve before headline rents do.
Demand holds, rent growth lags
National figures point to a market that is slowing rather than breaking. Yardi Matrix Senior Research Officer Doug Ressler describes it as one of “stable demand but limited pricing power,” with wide variation by market. SFR continues to modestly outperform conventional multifamily on rent growth, particularly where apartment supply is heavy, suggesting a pricing and lease-up challenge more than a broad demand problem.
John Burns Research and Consulting’s latest data show a similar pattern. Its Burns Build-to-Rent Index measured effective rent growth of just 0.2 percent year-over-year through August at matched, leased-up properties, while occupancy held at about 95 percent. The firm’s separate Single-Family Rent Index, which tracks new-lease asking rents, recorded 1.2 percent growth. Yardi Matrix reported 0.8 percent advertised rent growth across its SFR/BTR coverage. Because the indexes track different rent types and properties, their results are not directly comparable.
Other indicators underscore the variation. Arbor Realty Trust’s Single-Family Rental Investment Trends Report, produced in partnership with Chandan Economics, found that 98.1 percent of its tracked SFR markets posted positive annual rent growth in August, including more than 96 percent in the Sun Belt, up from less than 89 percent in February. Chandan Economics Vice President & Head of Research Jonathan O’Kane called this the “normalization in operating fundamentals, not a new normal in valuations.” But with SFR cap rates at 7.2 percent in the second quarter, he said higher Treasury and mortgage rates could put further pressure on cap rates if home prices weaken.
READ ALSO: How SFR Returns Are Dipping Across the US
JBREC, by contrast, found that SFR new-lease rent growth slowed during peak leasing season. Together, these figures suggest broad improvement in the share of markets with rent growth, but still limited momentum in new leases.
The demand base also extends beyond households priced out of homeownership. Urban Institute’s Laurie Goodman believes high home prices and borrowing costs have widened the gap between renting and owning, while BTR also attracts renters by choice and larger families. There is no long-term data available to show how many renters eventually buy.
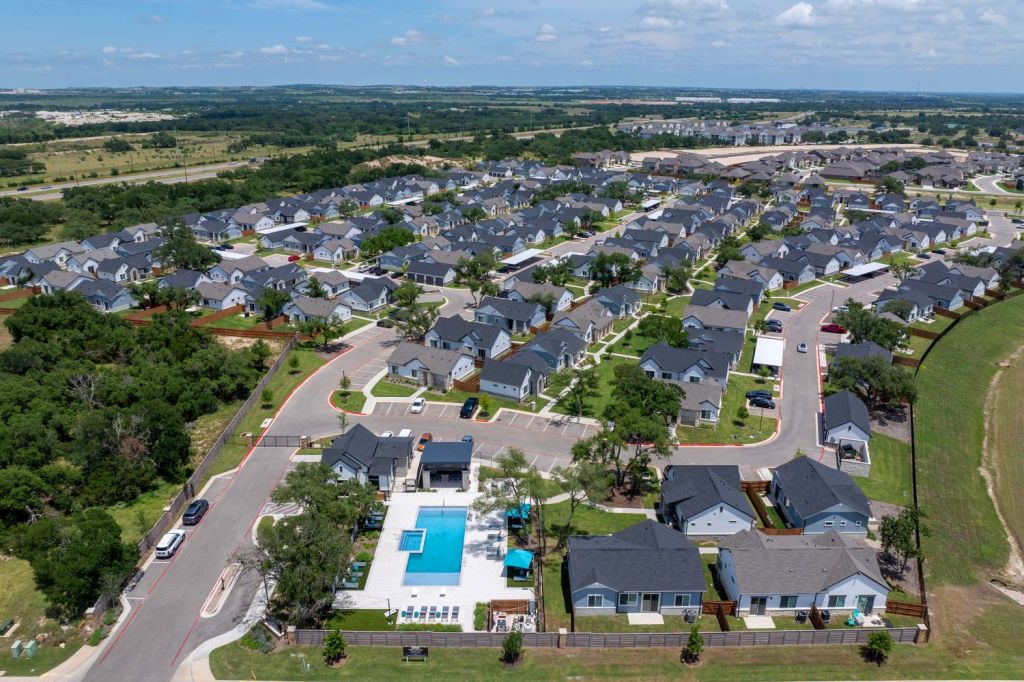
A neighborhood-scale rental community unfolds at Avilla Berry Creek Highlands in Georgetown, Texas. All images courtesy of NexMetro Communities 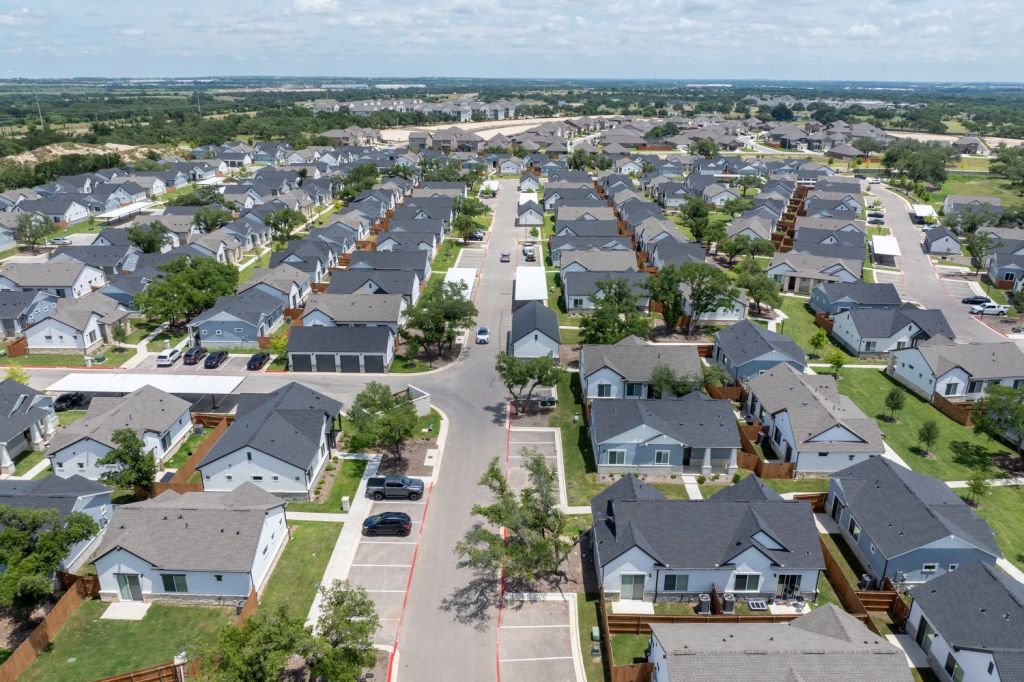
Purpose-built rental homes line private streets at Avilla Berry Creek Highlands. 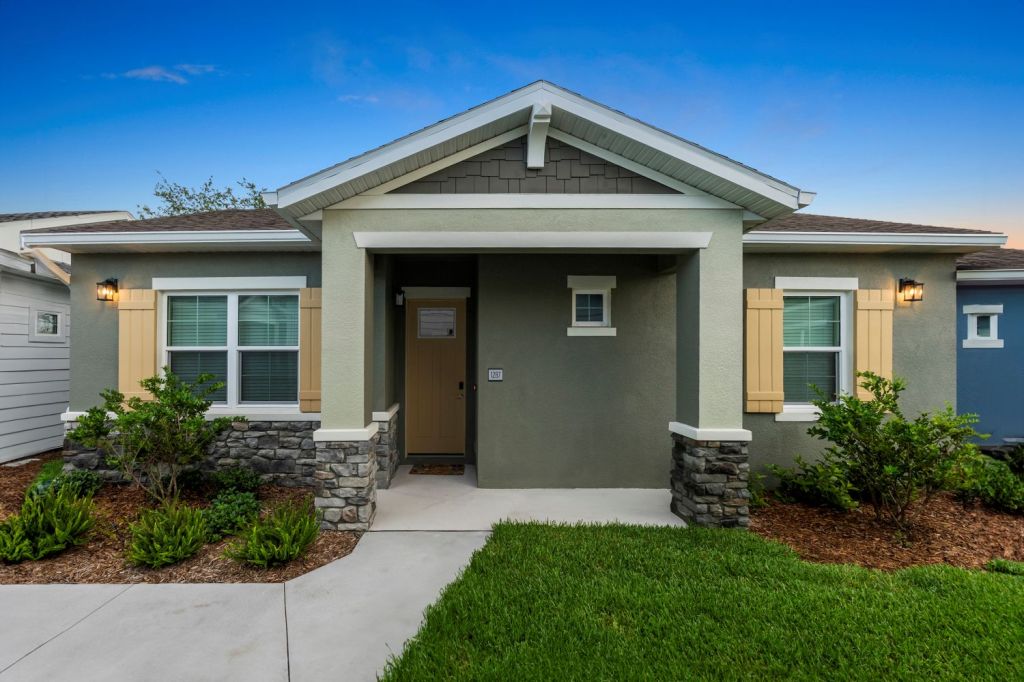
A single-story home at Avilla Cypress Creek in Sun City Center, Fla. 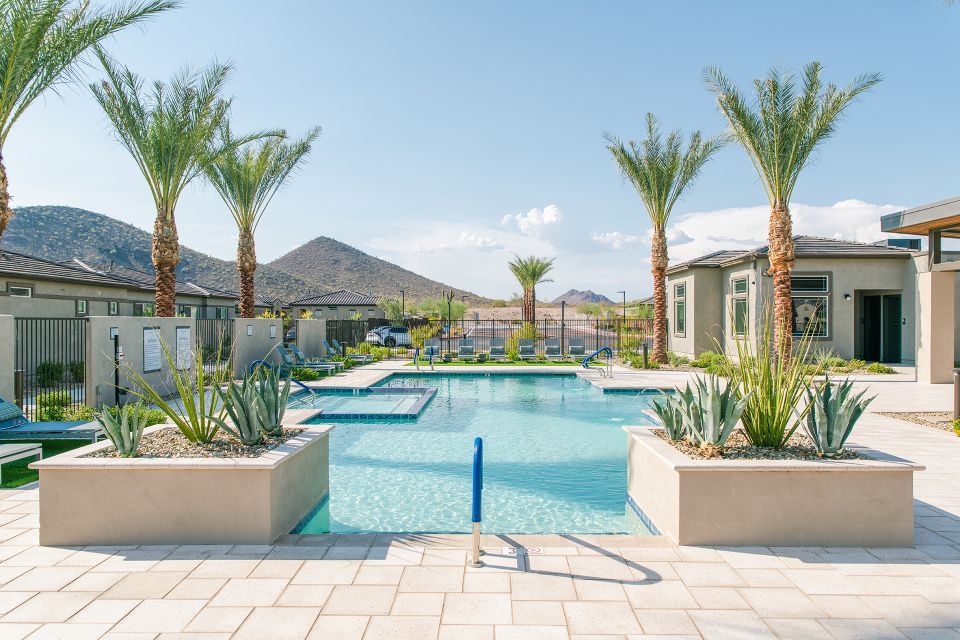
A shared pool and mountain views shape the outdoor setting at Avilla Mystic in Peoria, Ariz. 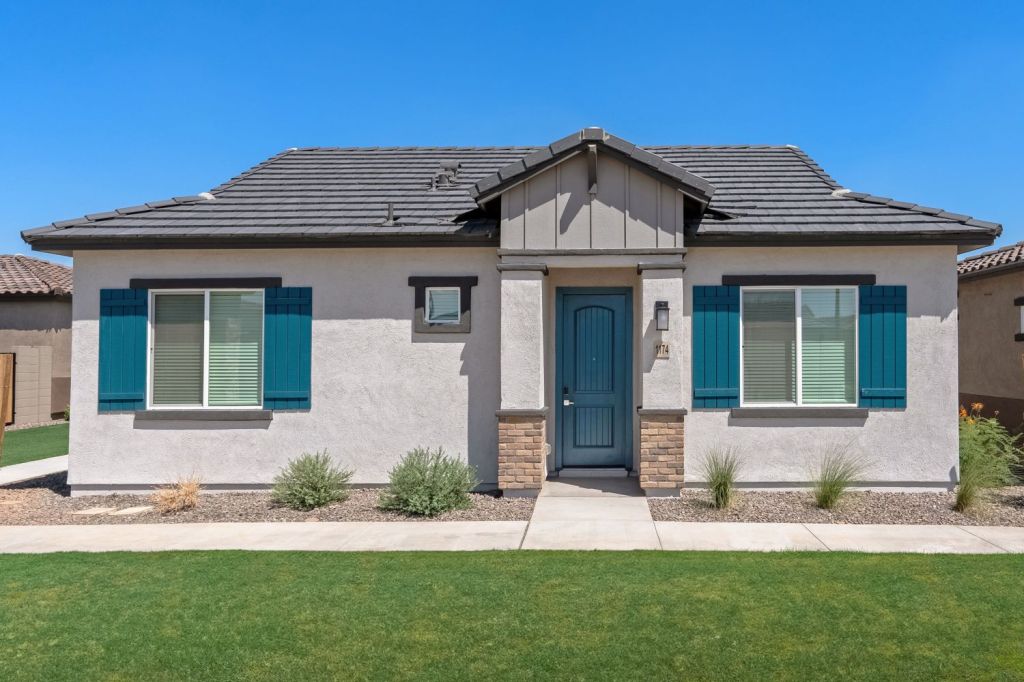
Blue shutters add a bright accent to an Avilla Palomino home in Glendale, Ariz. 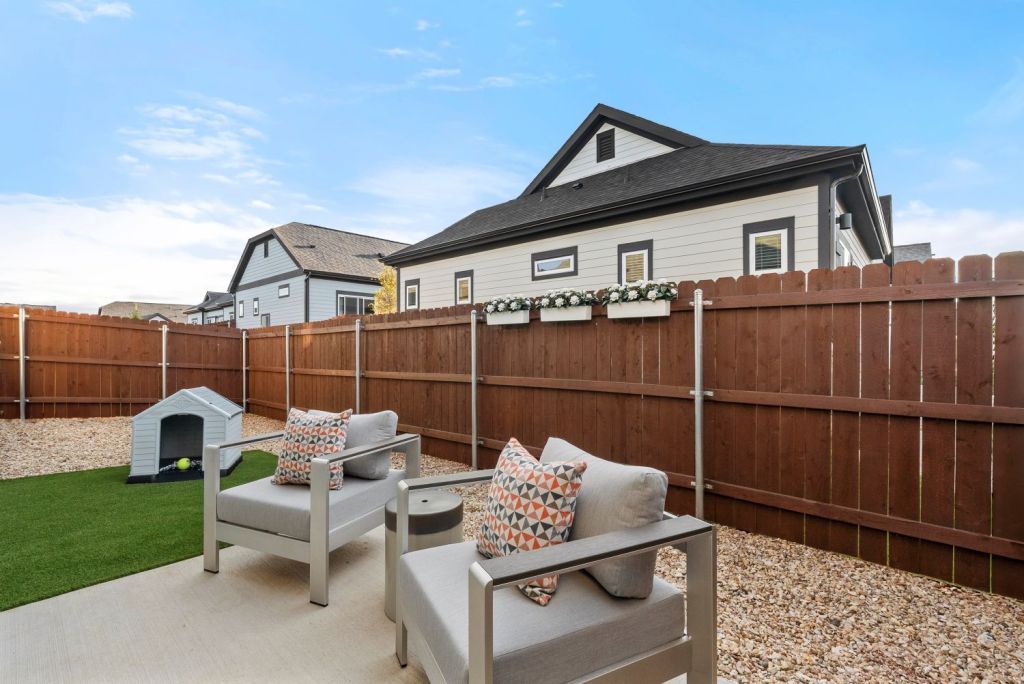
A private backyard extends the living space at Avilla Railhead in Cleburne, Texas. 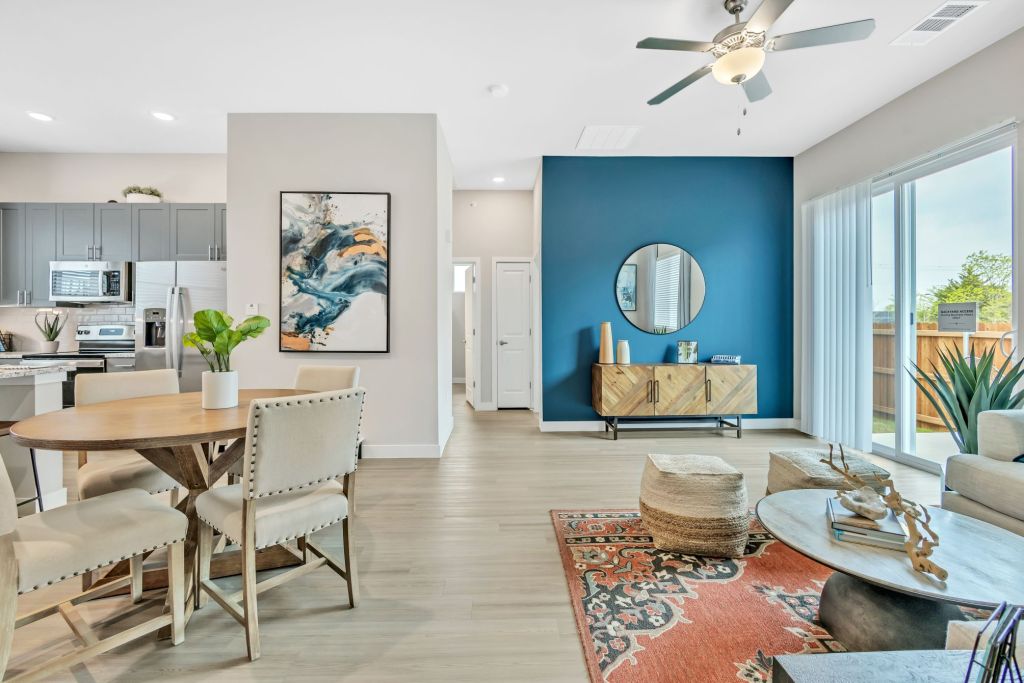
An open kitchen, dining area and living room form the great room at Avilla Towne Center in Princeton, Texas.
NexMetro Communities CEO Josh Hartmann, whose company develops cottage-style BTR homes under the Avilla brand, sees demand coming from households delaying homeownership, renters seeking more space and privacy than apartments can offer, and renters by choice. But attracting residents is only part of the equation.
“Residents choosing to renew and remain in an Avilla neighborhood is a stronger indication that the product is meeting their needs over the long term,” Hartmann said.
An uneven supply reset
The most favorable development for the sector is the expected decline in new deliveries. Yardi Matrix’s forecast, based on data available in July 2026, projects BTR completions to fall from 47,371 units in 2026 to 25,862 units in 2027, a drop of about 45 percent.
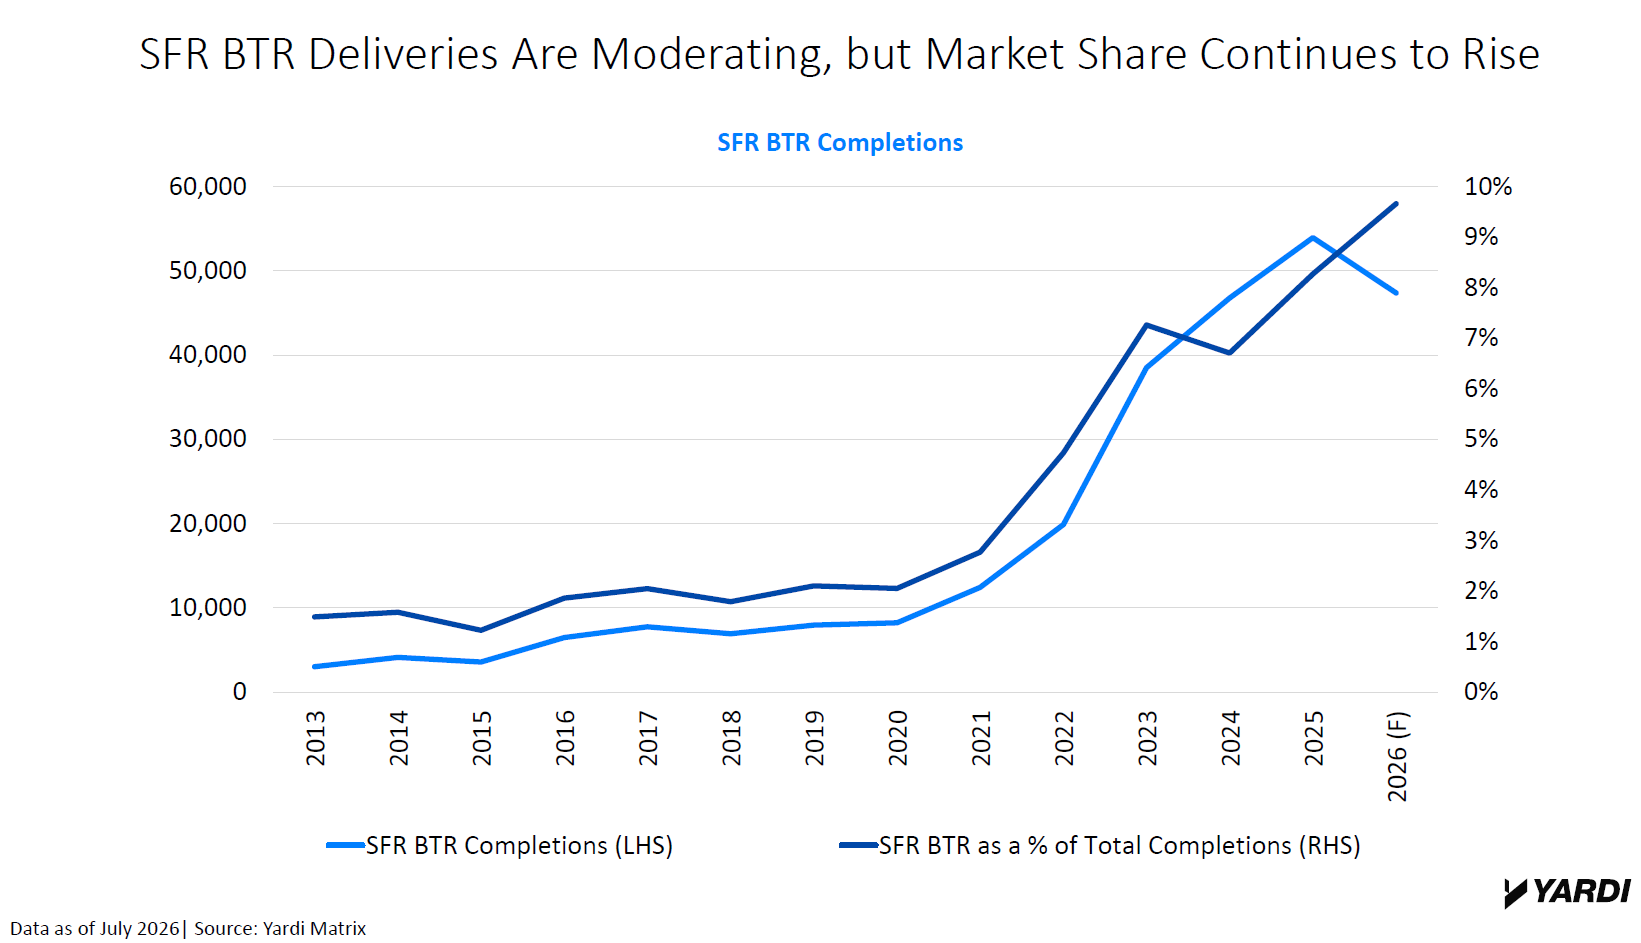
Fewer deliveries should give existing communities more room to stabilize, but the adjustment will take time. Markets with the largest supply waves still need to absorb homes under construction or in lease-up. Yardi has greater confidence in projects already underway than in longer-term planned pipelines, Ressler said, so the forecast’s further decline to 12,092 units in 2028 should not be read as a permanent supply ceiling.
The uneven absorption is already visible across markets. According to Yardi Matrix’s analysis, Miami, Jacksonville and Raleigh-Durham show comparatively strong SFR pricing. In Denver, apartment are weak while SFR is holding up better, suggesting SFR has more resilience. San Antonio, Greenville, S.C., and Pensacola, Fla., warrant closer attention: SFR rents are falling and underperforming multifamily, pointing to weakness within SFR rather than spillover from a soft apartment market.
Yardi’s July data show the range: Indianapolis (4.1 percent), Miami (4.0 percent) and Chicago (3.8 percent) lead year-over-year SFR/BTR rent growth, while San Antonio (-5.2 percent), Phoenix (-2.6 percent) and Austin (-2.4 percent) trailed.
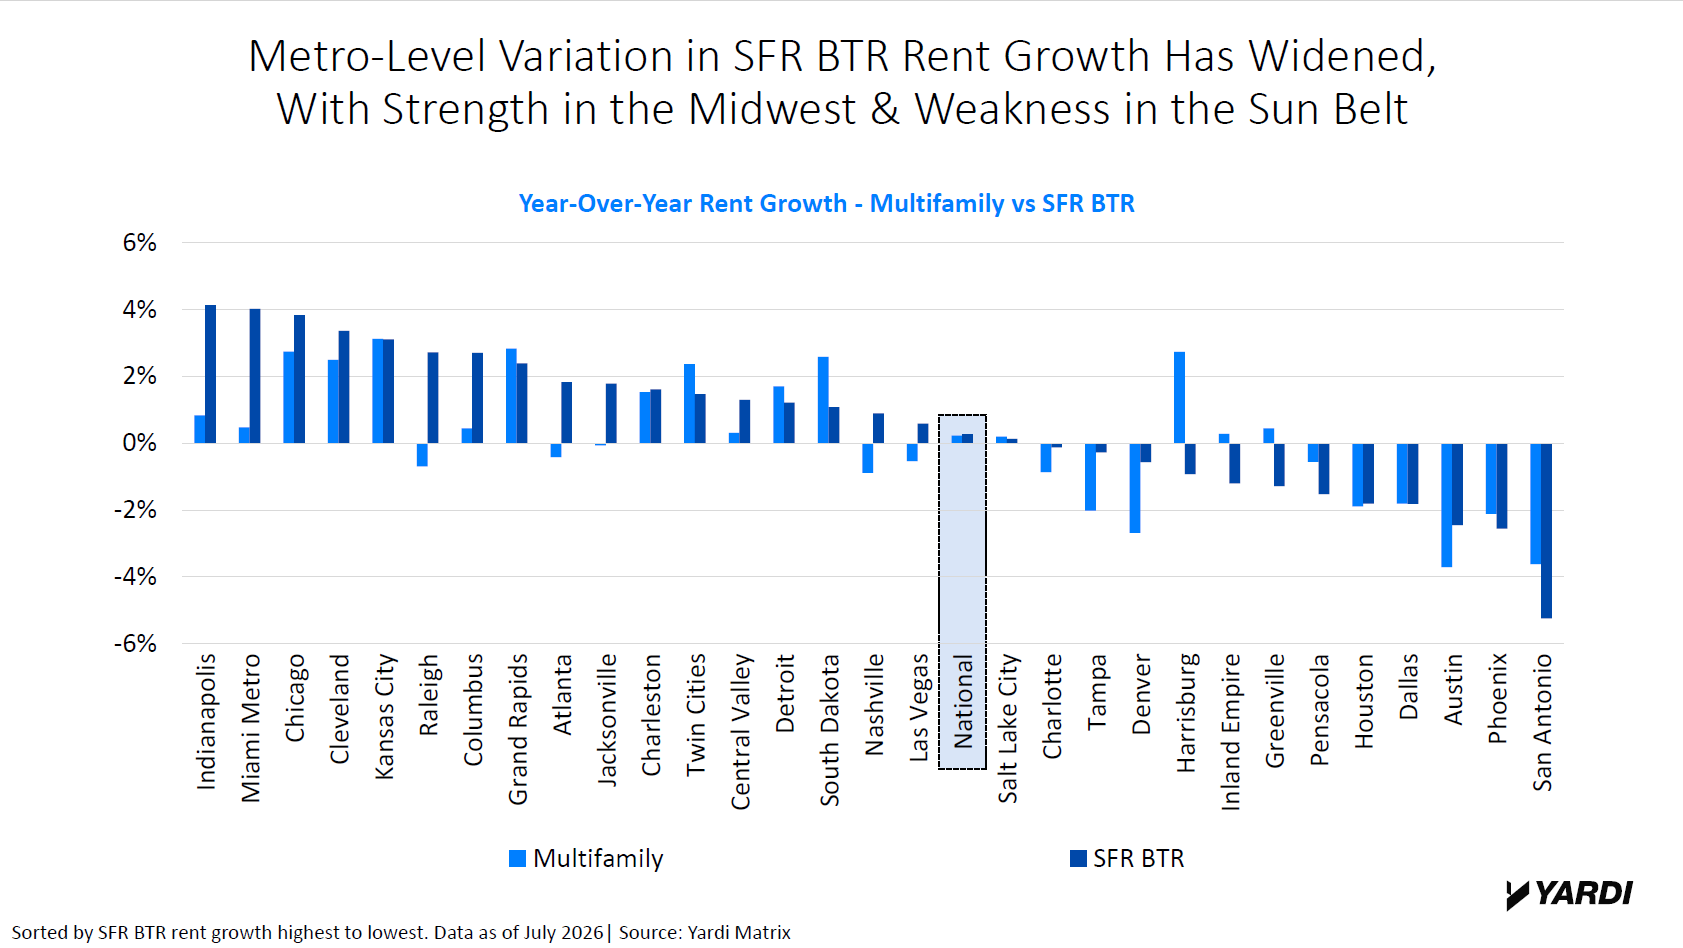
For 2027, the distinction between oversupply and weak demand matters. Ressler cautions against treating negative rent growth as proof of weak demand: If occupancy and absorption stabilize as deliveries crest, a market may simply be working through a temporary supply wave. Sustained occupancy deterioration alongside rent weakness would signal a more fundamental problem.
Net new supply is the measure Goodman would prioritize. Slower household formation—including later marriages, lower fertility and slower immigration—also means less housing construction overall, not just in BTR. JBREC expects BTR deliveries to fall by nearly half in 2027, with particularly steep declines in Atlanta, Austin, Houston, Orlando and Phoenix, and forecasts slightly positive national BTR rent growth.
The pace of recovery will therefore depend on how quickly individual markets absorb their remaining pipelines. Those with the steepest declines in new deliveries may have the greatest opportunity to regain balance, but the benefits will depend on the depth of existing supply pressures.
What renters will pay for
The product mix has shifted toward larger homes since 2020, according to Yardi Matrix’s August 2026 data. Larger floorplans, yards, garages and privacy underpin SFR/BTR’s appeal between conventional apartments and homeownership. Three-bedroom units now account for a larger share of deliveries, Ressler said, and Yardi’s research shows meaningful rent premiums for garage-equipped townhomes.
Still, detached homes do not automatically outperform attached formats. JBREC’s August matched-plan analysis found that single-level rowhomes posted the strongest effective rent growth (2.2 percent year over year) and the highest occupancy. Single-family detached homes were flat, while horizontal apartments or cottage communities had the weakest performance (-1.2 percent), despite leasing faster than other product types.
Geography helps explain the divergence. Rowhomes are concentrated in Midwest markets such as Cleveland, Columbus and Indianapolis, while cottages are heavily concentrated in Phoenix. The better test, therefore, is whether a community provides the features renters will pay for in a particular submarket.
RangeWater Real Estate, for example, has adjusted its development standards based on early lease-ups and investor feedback, including a more differentiated mix of bedroom types, floorplans and garage types, according to Chase Davidson, the company’s director of capital markets. Demand alone, however, does not guarantee returns.
Operating costs and exit caps have become the most consequential underwriting assumptions beyond lease-up rents. In practice, a community can attract renters and still miss return targets if its design, basis or operating profile do not fit the market.

Early signs of recovery
Operating performance may turn before headline rents do, but several metrics will need to move in the right direction. In its latest survey, JBREC found that BTR operating costs rose 4.6 percent year over year, cooling from 5.6 percent in the first quarter but still faster than rent growth. The measure combines repair, maintenance, turnover and insurance costs, putting pressure on NOI even where occupancy holds steady.
Concessions also need to be read alongside base rents. JBREC advises treating concessions as a lease-up expense and base-rent reductions as permanent. Operators across the Southeast told the firm that lowering base rents is working better than maintaining higher asking rents paired with concessions, a sign that some communities are resetting rent rolls rather than relying on temporary incentives.
READ ALSO: Lafayette’s Long-Term Bet on SFR
Markets that oversupplied most aggressively may see early improvement as their pipelines run down, but they could also face the longest concession hangover. As Hartmann put it, leasing at target pace only by offering six weeks of free rent means “you’ve bought time, not recovered.”
But no single metric will capture the turn. Hartmann emphasizes renewal and retention as the strongest measures of durable demand. JBREC tracks new-lease rents, concessions, absorption and move-outs, while Ressler looks at stabilized occupancy: If rents remain soft but occupancy holds, demand is intact; if occupancy declines persistently, the outlook is more concerning.
Leasing velocity and concessions can provide earlier signs, with occupancy serving as confirmation. Headline asking-rent growth may come last.
Capital follows the fundamentals
The focus on operating performance is shaping capital allocation. RangeWater is active across ground-up development, certificate-of-occupancy acquisitions and stabilized purchases because rate volatility has created relative value across the market. But tighter development margins have narrowed the company’s focus to sites where it has the strongest conviction in basis and exit.
The ROAD to Housing Act, which became law on July 11, 2026, prohibits covered institutional investors—those with direct or indirect investment control over at least 350 single-family homes—from purchasing single-family homes, subject to exceptions that include qualifying BTR programs.
The final law omitted an earlier proposal that would have required certain BTR properties to be sold within seven years. The carve-outs give institutions a clearer regulatory route into SFRs, but they do not change the core underwriting: development cost, lease-up, debt yield and local demand still determine lender appetite. O’Kane said it is too early to know whether the law has changed lenders’ approach.
RangeWater is already hearing from new capital sources interested in purpose-built BTR, Davidson said. The federal law established the framework, while state policy remains a source of uncertainty. On Oct. 23, Treasury published a proposed rule clarifying terms such as “build-to-rent program” and “program to boost homeownership”; but the final framework will determine how qualifying activity is documented.
Goodman is more cautious about how much the law changes in practice. The distinction between existing-home acquisitions and BTR may be “more in theory than in practice” given the statutory exemptions, she said. The “program to boost homeownership” exception requires positive rental-payment reporting for renters who are informed of and opt into the program, a right of first refusal and a 30-day “first look” period. Even with a clearer path, high interest rates and return requirements remain more consequential constraints.
The larger risks are economic. Ressler sees the main downside as supply pressure lasting long enough to turn a pricing problem into an occupancy problem. O’Kane points to sustained labor-market deterioration, particularly if unemployment rises above 5 percent while household income growth weakens. Because SFR generally serves households at a higher price point than conventional multifamily, employment stability will be especially important.
The 2027 outlook is therefore one of selectivity: lower supply, demand that remains present but offers limited pricing power, and capital favoring projects able to withstand slower rent growth and higher operating costs. A healthier market will be defined by balance: communities leasing without excessive incentives, residents renewing without unsustainable increases and projects moving forward only where local economics support them.