Affordable Housing Refinancing: Difficult But Doable
It's getting even harder these days, especially when owners can't raise rents.
It’s getting even harder to refinance, especially when your ability to raise rents is limited.
Affordable housing investors and developers face somewhat of a paradox. At a time of rising loan originations and a widespread recognition on Washington’s part that we need to preserve the nation’s existing stock, the cost of capital remains stubbornly high and operational expenses are going nowhere but up.
Some $10.5 billion in mortgages backed by fully affordable properties are coming due over the next three years, according to Yardi Matrix. Through the end of the decade, $21.7 billion of these mortages are set to mature.
But determined owners are still finding ways to preserve their inventory and actively pursue new acquisitions and developments with the help of state-and federally backed financing tools.
Scaling the maturity wall
The 10-year Treasury rate has been hovering around 5 percent, which is considerably higher than earlier in the decade when many of the maturning loans were originated. When it comes to refinancing notes that were taken out in the last decade, the capital cost disparity might come as a shock to owners.
The loans facing the biggest refinancing headwinds are those closed in the last five years on properties currently in the lease-up phase and those that were originated a decade ago.
For Dominium Apartments, one of the nation’s largest owners of affordable housing, the loans facing the greatest refinancing challenges are those that the company closed on between 2022 through 2024 that are still not stabilized, according to Katessa Archer, vice president & project partner.
“These have some commitments on the front end from long-term permanent mortgage lenders, but the question really is, can we get these properties stabilized and leased up in today’s environment with the debt figures that we need to support the business plan?” Archer noted. “It’s a unique situation, and rising rates are not helping us in any capacity.”
READ ALSO: Waiting for Lower Rates Could Cost Multifamily Borrowers
Stabilizing properties is half the battle. Affordable developments rarely succeed purely on the balance sheet even in the best of times, requiring significan subsidies. “Higher rates make deals harder and a return on equity more difficult to achieve,” said David Leopold, Berkadia’s head of affordable housing. The higher rate environment has led to more complex capital stacks, which in turn have put greater pressure on subsidies.
“More need for subsidies means more credits per deal, which in turn means higher (-priced) deals, and lower prices per credit,” Leopold detailed.
Of course, the owners aren’t the only ones struggling to make ends meet. Renters are increasingly burdened by rising inflation. Data from a March 2026 study from Harvard’s Joint Center for Housing Studies showed that 22.7 million renter households are cost-burdened, a figure that averages out at 56 percent across income brackets.
“I call this a triple whammy,” said Margaret Salazar, CEO of REACH Community Development, an affordable housing organization with more than 2,800 units across Washington and Oregon. “We have the rising interest rates and inflation, but we also have folks that are struggling to keep up with rents,” Salazar told Multi-Housing News. “At the same time, we’re also finding that it’s harder for us to get financing to preserve our existing properties. It really is a perfect storm.”
Even for owners more insulated from the acute refinancing pressures, there’s a heightened sense of caution when pursuing investments. Avanath Capital Management, which manages approximately $3.7 billion in assets, invests in affordable housing through an open-end fund capped at 50 percent loan-to-value as a hedge against the rising debt pressures.
“We’re seeing loans that we originated 10 years ago at much lower rates, and now we have to refinance some 200 basis points more or higher,” said Ken McMackin, the firm’s executive vice president of investments. “It just puts a lot more pressure on executing efficiently.”
The push for preservation
Financing pressures threaten both the preservation of existing affordable housing and the development of new communities.
Dominium has faced a change in its need for tax-exempt private activity bonds for new projects, especially after the 50 percent test became the 25 percent test in the One Big Beautiful Bill Act. As a result, the firm has had to replace these with more expensive taxable debt, where the cost advantage is diluted. “We’re just not seeing that release to make affordable housing pencil, which in turn makes preservation and development more difficult,” Archer noted.
Even if the financing does exist, budget cuts from the federal, state and local governments have made gap financing more difficult to come by—even with a recent expansion of Low Income Housing Tax Credit availability for fiscal year 2026. There’s a conundrum here, according to Leopold: “Yield expectations for LIHTC investors are going up, which means that pricing and the amount of equity going into your deal is going down,” Leopold detailed.
Still, the reality is hard to ignore. “Us not having the financing to fill those gaps makes it harder for us to break ground,” Salazar said, “but even when we can, it’s difficult to get pre-development financing that we can afford at reasonable rates.”
Ports in the storm
When it comes to keeping their existing properties affordable, some owners are far better positioned than others. “The efficiency is just in numbers,” said John Ducey, senior vice president & chief production of affordable housing debt at Walker & Dunlop. “Since they have that economy of scale, they’re going to be stronger and will be able to maintain their operating margins better.”
For Dominium, a shift in unit sizes and more diversified approach to its renter base has allowed it to keep reasonable margins on projects with larger bedroom sizes. “If we can keep the financing efficient, we can also better diversify who we’re serving,” Archer noted.
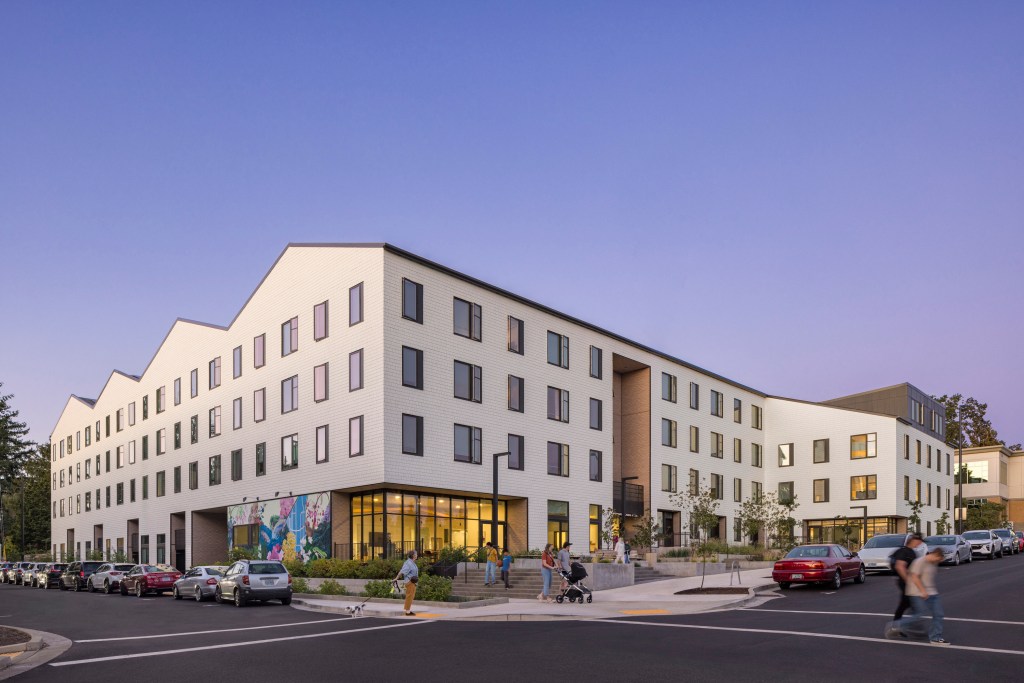
Others see their difficulties in procuring permanent financing as driving a greater need for operational efficiency. “The first thing we do is figure out how we can bring those costs down,” said Bart Mitchell, president & CEO of The Community Builders, which owns and operates 16,000 apartments around the Northeast, Midwest and Mid-Atlantic regions. “That can be anything from adding new insulation, upgrading to more efficient equipment or even adding rooftop solar to offset our utility costs.”
READ ALSO: Multifamily Has a Lot to Gain—And Lose—in the Midterms
Some owners have grown to rely more on third parties. REACH has pivoted to using third-party property management, in addition to boosting advertising [SPEND] for vacant units. The company’s properties around Portland also benefit from the city’s Clean Energy Fund, which has unlocked some gap financing for preservation deals. “The city has an interest in trying to get units filled as quickly as possible because of our supply challenges, and that’s been a huge boon for us,” Salazar noted.
Even in the most difficult of circumstances, financing is still doable. “They’ll look at resyndication opportunities or presevering, even with lower targeting,” Leopold explained. “Even if area median income restrictions shift up a little bit, that’ll be exchanged for more shallow subsidies. At the same time, there have never been more states with their own tax credits, which further help deals pencil.”
Section 8 vouchers and state tax credits also fill critical gaps, but the true lifeline has been the GSEs, which increased their purchase caps to $88 billion apiece at the start of this year. “They’ve been our bread and butter, and our most reliable source of debt,” McMackin said.
A helping hand
Alongside the abundance of state tax credit offerings, some new legislation has the potential to further help affordable stakeholders bridge financing gaps. The most prominent of these pro-housing measures has been the 21st Century ROAD to Housing Act, which became law in July.
In terms of financing, the most notable provision in the act is raising of public welfare investment caps from national and state member banks from 15 to 20 percent, a move that could both ease the pressure on state-level subsidies and open up more LIHTC equity. According to Archer, this will improving pricing as subsidies fill. “It’s definitely a positive on the supply side, especially with how important the economics are to making (affordable) projects a reality.”
Still, it’s no substitute for private activity bonds, according to Archer.
Ducey welcomes the move but doesn’t see it providing longer-term fixes to the refinancing barriers borrowers face.
“It’s creating some new programs, but not the sort of appropriations at the level we need them to be to support new supply,” he reflected. “We have a real more of an income problem than a housing problem in some ways, and the federal government needs to address that with significant capital.”