San Antonio Multifamily Report – October 2026
Oversupply remains a factor in the short to medium term.
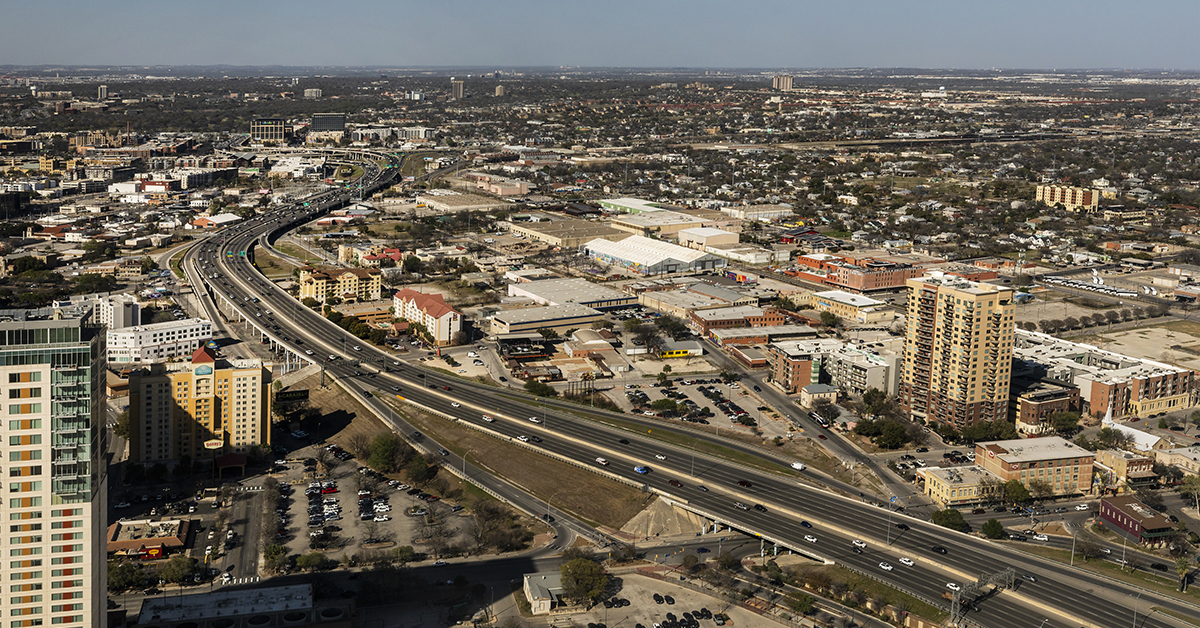
San Antonio’s wall of deliveries continued to intensify competition, keeping apartment fundamentals under pressure. Advertised asking rents slid 0.2 percent, on a trailing three-month basis through August, and were down 3.4 percent year-over-year, ranking below all of Yardi Matrix’s top 30 markets. Occupancy in stabilized assets declined 90 basis points, to 89.4 percent in July, as an influx of new Lifestyle communities intensified pressure on older RBN properties.
Job gains stood at 0.3 percent through June, ahead of a flat U.S. reading, as the area added 7,200 net jobs over 12 months. Trade, transportation and utilities (8,300 jobs) and professional and business services (5,500) led gains, while government recorded the largest slide (-6,800). Unemployment stood at 4.7 percent in July, above the 4.5 percent Texas and 4.4 percent U.S. rates. In a boost for the local economy, JCB’s $500 million South Side plant is scheduled to begin production this fall and create some 1,500 jobs over five years.
Development momentum remained strong, with 5,750 units delivered during the first eight months of 2026 and another 9,698 units underway as of August. Starts saw a 5.6 percent uptick from the corresponding period of 2025, suggesting that supply pressures are here to stay. Investment was also up from last year’s slower start, with deal volume increasing 27 percent, to $252 million. Even so, the rebound was modest considering the wider context.