Manufactured Housing’s Fundamentals Are Built to Last
Natural affordability is just one of its appealing features.
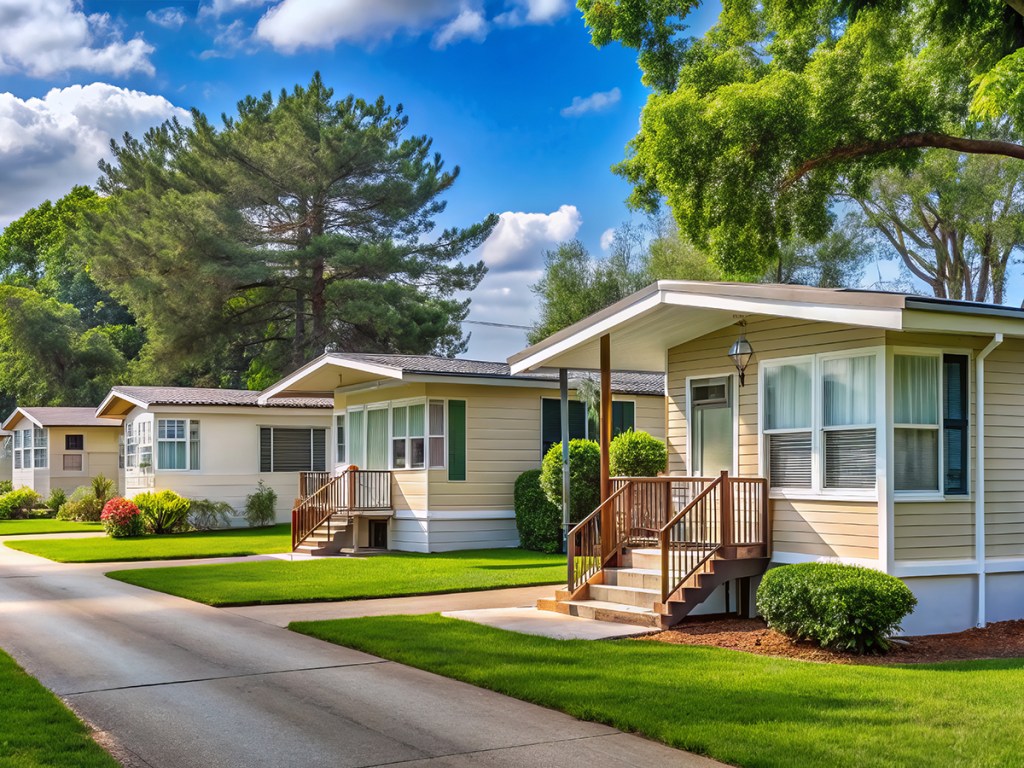
As institutional investors continue searching for stable income and long-term growth, manufactured housing has emerged as one of the most compelling opportunities in the real estate market.
While the sector rarely commands the same attention as office, industrial or multifamily assets, its fundamentals have remained remarkably consistent: strong demand, limited supply and resilient cash flows.
Transaction activity remained active throughout 2025 and into 2026, with private buyers continuing to account for the majority of acquisitions. The Sun Belt, Southwest and North Carolina remain among the most active markets, and cap rates have stayed relatively stable despite volatility across other commercial real estate sectors. Behind that stability is a structural story that investors are finding increasingly difficult to ignore.
The affordability gap isn’t closing
The investment thesis for manufactured housing communities has always centered on affordability. What’s changed is who is paying attention. Institutional capital has increasingly moved into a sector once dominated by smaller regional operators. The need for affordable housing is not easing, and manufactured housing is one of the few asset classes where supply constraints are truly structural.
LIKE THIS CONTENT? Subscribe to MHN’s Finance & Investment Newsletter
Only 5 percent of manufactured housing communities have been developed since 1990. That is not a temporary slowdown driven by financing challenges or construction costs. It is the result of zoning restrictions, community opposition and the regulatory hurdles required to bring new communities online. Investors value that dynamic because limited new supply creates a competitive advantage that is difficult to replicate.
The tenant owns the home. That matters
Understanding MHCs requires an understanding of what separates them from other residential asset classes. The resident owns the home. The operator owns the land. That structure creates something unusual in residential real estate: Residents have a strong financial incentive to stay.
Average tenure often approaches 10 years. When residents own their homes, moving is costly and often impractical. As a result, occupancy tends to remain stable through economic cycles. That predictability translates directly into underwriting and helps produce cash flows that have historically been more resilient than many traditional multifamily properties. Leases are typically month-to-month, but turnover remains exceptionally low.
The value-add playbook
For investors pursuing value-add strategies, infill opportunities remain one of the sector’s most attractive characteristics. Communities with vacant sites can create value by bringing in new manufactured homes, which range from $60,000 to $90,000 for single-section units and $95,000 to $150,000 for multi-section units, while adjusting lot rents to reflect current market conditions.
The strategy benefits both operators and residents. Operators increase occupancy and grow net operating income while homeowners gain access to affordable housing and the opportunity to build equity. Over time, stabilized occupancy can strengthen community performance and support long-term value creation.
Success, however, depends on execution. Identifying the right asset, in the right market, with the right regulatory environment requires careful diligence and local market knowledge.
Regulatory risk is real, but manageable
Rent regulation has become a growing consideration for MHC investors. States such as California and Washington have adopted various forms of rent control, while similar discussions continue in other markets across the country.
Although regulatory concerns have not materially slowed transaction activity, they have influenced investor behavior. Capital is becoming more selective, with buyers placing greater emphasis on state and local policy environments during acquisition underwriting. The conversation may be national, but the impact is often determined at the state level.
Expense pressure
Operating expenses have become an increasingly important focus for owners and investors. Insurance costs, particularly in Florida and other storm-prone regions, continue to rise. Aging utility infrastructure and broader inflationary pressures are creating additional expense challenges across the sector.
Unlike some property types, manufactured housing communities often have fewer ancillary income streams available to offset rising costs. That makes expense management a critical component of long-term performance.
Institutional investors should also understand an important distinction in the valuation process. Appraisals of manufactured housing communities generally reflect the value of the real estate itself—not the personal property located on-site. Manufactured homes and recreational vehicles are typically considered personal property and are not included in the real estate valuation.
That distinction can create confusion for investors and lenders entering the sector. Understanding how value is measured is essential to underwriting, financing and accurately assessing investment performance.
The opportunity ahead
Manufactured housing continues to attract institutional capital because the sector’s core fundamentals remain intact. The demand for affordable housing is structural. New supply remains constrained. Resident tenure is long, and cash flows are highly predictable.
The risks are real. Regulatory changes, rising insurance costs and the execution required to successfully implement an infill strategy all deserve careful consideration. Yet these are largely knowable risks that can be evaluated through disciplined underwriting.
For investors seeking durable income and long-term housing exposure, manufactured housing remains one of the most compelling sectors in commercial real estate. The opportunity begins with understanding a simple reality: In a market defined by housing scarcity, existing communities are becoming increasingly valuable assets.
David Bernstein is a senior director within JLL’s Valuation Advisory group specializing in manufactured housing and recreational vehicle communities.
Please note: To become a Viewpoint writer, reach out to Therese Fitzgerald at therese.fitzgerald@cpe-mhn.com. All Viewpoints are copyright of Multi-Housing News 2026. We do not accept AI-written content.